Verification
We chase the references. Plaid verifies the bank.
The two things that make a credit file trustworthy are the two things nobody on your team has time for: getting suppliers to answer, and getting a straight look at the bank account. Credlab does both.
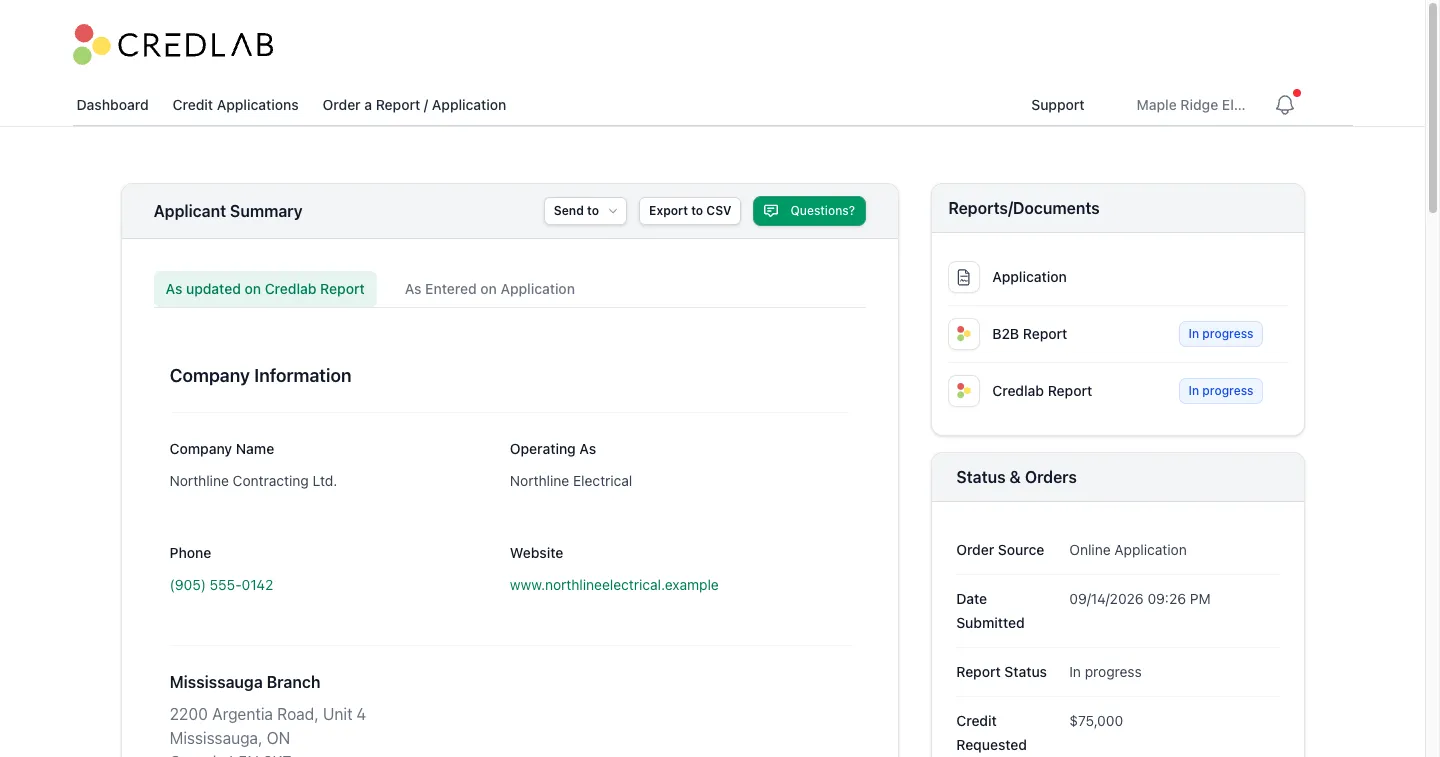
Trade references, chased by our analysts. Not by you.
Most reference requests die in a supplier's inbox. Ours don't, because a person in Toronto is on the phone following up, and it isn't someone from your credit department.
- References we already hold go in first. If we have references on file for the company from previous reports, they're part of the picture from day one.
- The ones on the application get a self-service link. Suppliers reply in a minute, without an account and without a PDF.
- The ones who don't reply get a call. And another. If a reference still can't be reached, the report says so. Every reply and every call note lands in the file, next to the application.
- Payment behaviour goes into the report. How much they buy, how they pay and whether they pay on time feed the payment window and the suggested limit in the Credlab Report.
The bank account, verified. Not a statement someone emailed you.
A PDF bank statement can say anything. With Credlab, the applicant connects their business account through Plaid as a step in the online credit application. It's read-only, made with their explicit consent, and their banking credentials never touch Credlab. What comes back is a verified picture of the account:
- Account holder, matched to the applicant.
- Institution, account type and current balance.
- Up to 24 months of transactions.
- Average monthly deposits and withdrawals, month by month.
- NSF and overdraft items, counted and dated.
- A written bank analysis, generated with AI from the Plaid data and labelled as such, so nobody on your team has to read 24 months of transactions to find the story.
Nothing to chase, nothing to doctor, and nothing for your team to store: the analysis sits in the file with everything else, under the same role-based permissions and audit log as the rest of Credlab.
Why it matters
A credit decision is only as good as the two things a bureau can't tell you: whether the company's own suppliers get paid, and whether there's money in the account. Credlab puts a person on the first and Plaid on the second, and puts both in front of your credit manager before they decide.
See it on a real file. Book a demo and bring an application you're working on now.
Questions we get asked
What happens when a reference never replies?
A Credlab analyst calls, and calls again. If a reference still can't be reached, that is recorded in the file too, and the report says so, because a supplier who won't vouch for a customer is information in itself.
Can we make bank verification a required step?
Yes. You decide per location whether an applicant must connect a bank account to submit. Many teams require it above a certain credit limit and leave it optional below.
Which banks does it work with?
Plaid connects to most Canadian and US financial institutions. The applicant picks their bank from Plaid's list and signs in there, never on Credlab.
How far back does the bank data go?
Up to 24 months of transactions, depending on what the bank makes available. The summary shows average monthly deposits and withdrawals, the date range covered and any NSF or overdraft items.
Does Credlab ever see the applicant's banking password?
No. The connection is made on Plaid's screens, is read-only, and no credentials pass through or are stored by Credlab.
Your first analyst-reviewed credit report, back in about 48 hours.
Start a 30-day free trial, or bring two or three real applications to a demo and we'll walk them through Credlab end to end.